Market data
The economy behind Uganda's property market: 6.3% growth, 3.1% inflation, a steady shilling
Growth of 6.3%, inflation at 3.1%, a shilling up 2.4% and a record balance of payments surplus. The macro picture that sits underneath every rent, price and loan in Kampala.
Yellow Bricks Uganda team · 9 September 2026 · 3 min read
Property prices are usually explained street by street: this suburb is hot, that road is finished, this land has a clean title. All true, and all sitting on top of something bigger. Knight Frank Uganda's H2 2025 review opens with the economy, and it is worth reading in that order.
- Economic growth rate, FY 2024/25
- 6.3%
- Economic growth rate, FY 2024/25
- Headline and core inflation, December 2025
- 3.1%
- Headline and core inflation, December 2025
- Central Bank Rate, December 2025
- 9.75%
- Central Bank Rate, December 2025
- Annual Uganda shilling appreciation to December 2025
- 2.4%
- Annual Uganda shilling appreciation to December 2025
Source: Knight Frank Uganda, Kampala Property Market Performance Review, H2 2025, citing Uganda Bureau of Statistics and Bank of Uganda data.
Growth is back where it was before the pandemic
The report's GDP series tells a clean story. Growth ran at 6.3% in 2018/19, fell to 3% and 3.5% through the pandemic years, then climbed steadily back: 4.6%, 5.2%, 6.1% and 6.3% in 2024/25. Uganda has spent five years recovering the ground it lost, and has now recovered it.
Source: Knight Frank Uganda, Kampala Property Market Performance Review, H2 2025, citing Uganda Bureau of Statistics and Bank of Uganda data.
Prices are calm, borrowing is not
Headline inflation fell from 3.8% in July to 3.1% in December, and core inflation from 4.2% to 3.1% — its lowest in nearly two years and comfortably below the Bank of Uganda's 5% medium-term target. The Bank held the Central Bank Rate at 9.75% throughout. Calm prices, though, did not make loans cheap: commercial banks' shilling lending rates still averaged 19.07%. That disconnect is the reason a stable economy can sit alongside a property market where most purchases never involve a bank.
Headline and core inflation, July to December 2025.
Source: Knight Frank Uganda, Kampala Property Market Performance Review, H2 2025, citing Uganda Bureau of Statistics and Bank of Uganda data.
A stronger shilling and a record surplus
The shilling appreciated 2.4% over the year to December 2025, and Uganda recorded a balance of payments surplus of US$2.37 billion. For anyone holding a dollar-denominated loan or paying dollar rent — common in prime Kampala and across commercial property — a stronger shilling quietly reduced the bill. It can just as quietly increase it again.
Real estate as an industry
Real estate output rose from UGX 3,323 billion in Q3 2025 to UGX 3,343 billion in Q4 2025, about 0.6% quarter-on-quarter growth, following UGX 3,117 billion and UGX 3,187 billion earlier in the year. Steady rather than spectacular, and driven by urbanisation, infrastructure investment and continued development activity.
UGX billions, current prices.
Source: Knight Frank Uganda, Kampala Property Market Performance Review, H2 2025, citing Uganda Bureau of Statistics and Bank of Uganda data.
A growing economy with expensive credit produces exactly the market Uganda has: plenty of building, very little borrowing.
What to watch next
- Commercial oil production targeted for the second half of 2026, and the industrial and logistics demand running ahead of it.
- Infrastructure delivery — Kabaale international airport, the pipeline, the standard gauge railway, Nakivubo and Kampala's road works — which changes which areas are convenient.
- Coffee exports, which reached US$2.4 billion and are pulling warehouse demand with them.
- Whether lending rates ever follow the policy rate down. Nothing widens home ownership faster than credit that ordinary earners can service.
What this means for you
- Growth of 6.3% in FY 2024/25 puts Uganda back at pre-pandemic pace.
- Inflation of 3.1% and a policy rate of 9.75% mean a stable macro backdrop.
- Shilling appreciation of 2.4% and a US$2.37bn balance of payments surplus supported dollar-denominated obligations.
- Real estate output grew modestly each quarter of 2025 to UGX 3,343 billion in Q4.
- Stable prices have not produced affordable loans, which is why cash and staged building still dominate.
General information only, not financial advice. The full review is published by Knight Frank Uganda at knightfrank.ug.
Where Yellow Bricks fits
We are a fixed-fee estate agency built for Uganda: every listing starts with a pin on the map, a drawn and measured boundary, and ownership documents reviewed before it goes live. This article is general information, not legal or financial advice — use your own lawyer and surveyor.
Keep reading
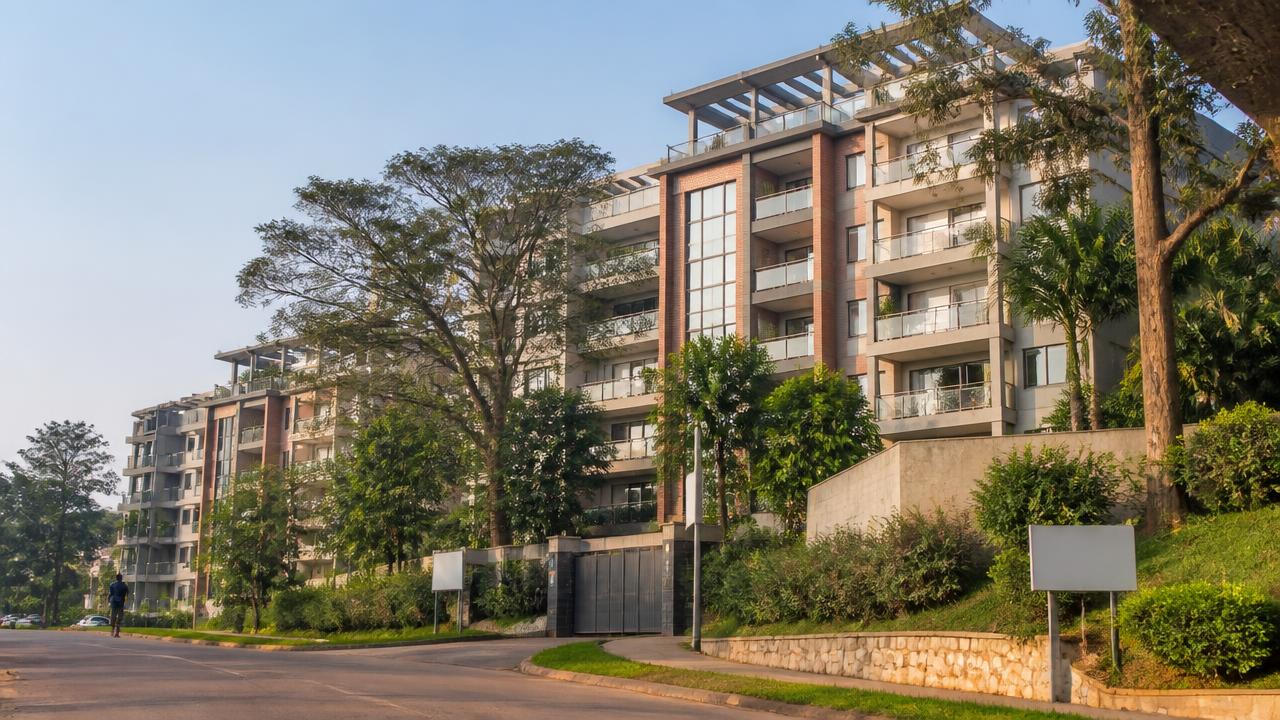
Kampala rents have turned in the tenant's favour — what the numbers say
Prime two-bedroom rents fell about 10% and three-bedroom rents about 9% over the year, while occupancy edged up. Here is what that means if you are renting or letting a home in Kampala today.
15 September 2026 · 3 min read
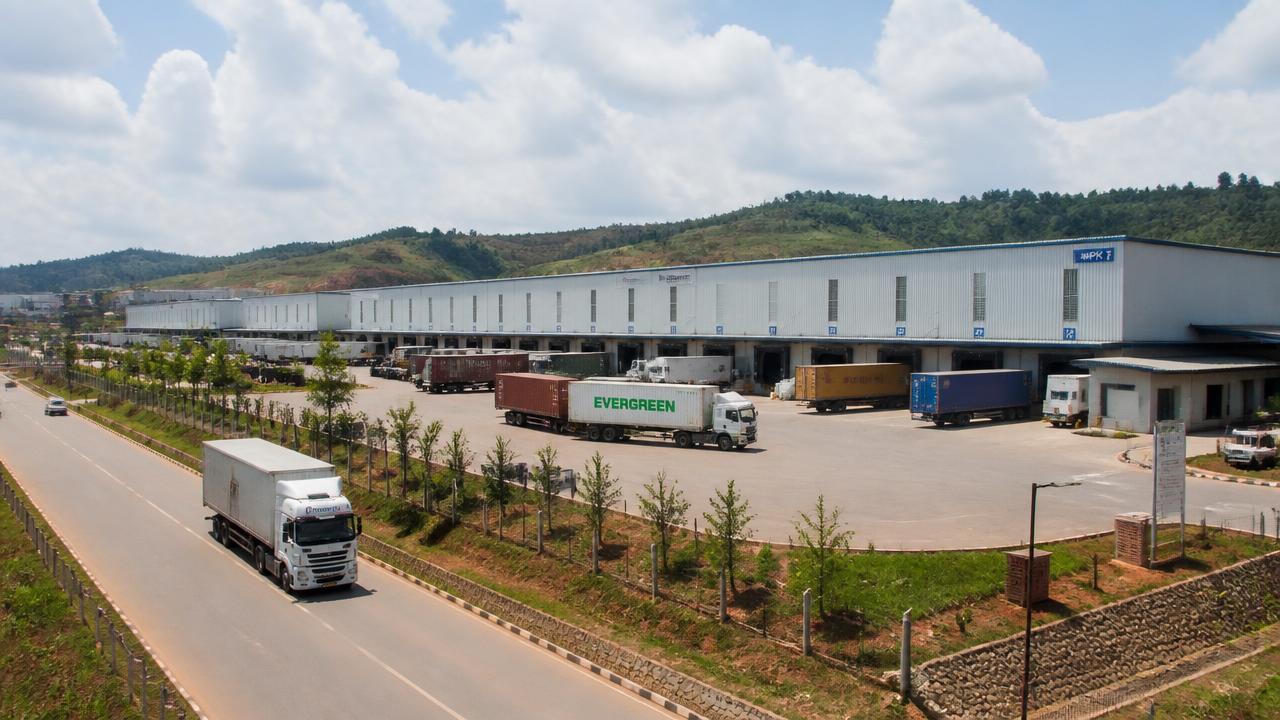
Where the money is going: warehouses and suburban retail are outperforming homes
While prime home rents fell, industrial occupancy held above 80% and mall footfall rose about 15%. A look at which parts of Kampala property are actually working, and what that means for ordinary investors.
13 September 2026 · 3 min read
What it costs to borrow for property in Uganda right now
The Central Bank Rate sat at 9.75% while banks lent shillings at an average 19.07%. Here is why property borrowing is expensive, who is getting approved, and what to ask a bank before you sign.
11 September 2026 · 3 min read